
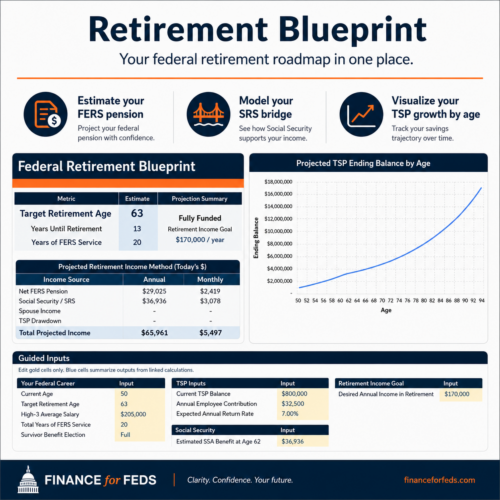
When can I retire? Try the Finance for Feds Retirement Blueprint™
Take the Guesswork Out of Federal Retirement: The Complete FERS & TSP Roadmap
Planning for federal retirement can often feel like trying to assemble a complex financial puzzle with pieces scattered across different agencies, HR portals, and outdated policy manuals. Between estimating your Federal Employees Retirement System (FERS) basic annuity, modeling Thrift Savings Plan (TSP) compound growth across C, S, and I funds, calculating your Special Retirement Supplement (SRS), and accounting for mandatory deductions, many federal workers are left relying on rough back-of-the-napkin math or generic retirement calculators that simply don’t understand civil service rules.
The Finance for Feds Retirement Blueprint™ was engineered specifically to replace guess-work with institutional-grade financial clarity.
Whether you are ten years away from your Minimum Retirement Age (MRA) or finalizing your retirement application package today, establishing a complete, household-level view of your federal cash flow is the single most effective step you can take toward a secure retirement.
The 4 Core Pillars of Federal Retirement Readiness
A comprehensive federal retirement plan must bridge the gap between your gross entitlement formulas and the net take-home deposit that arrives in your bank account on the first business day of every month. The Retirement Blueprint focuses on four non-negotiable structural pillars:
The 4 Core Pillars of Your Federal Retirement Blueprint
A complete household-level view of your federal retirement readiness and take-home cash flow.
3 Critical Pitfalls Standard Retirement Planning Misses
1. Miscalculating High-3 Salary & Sick Leave Conversion
Many federal employees assume their High-3 average salary is simply their final GS pay step or their top W-2 gross box. In reality, High-3 is calculated strictly from basic pay across 36 consecutive months, including locality pay and special salary rates, but excluding overtime, cash bonuses, and awards.
Furthermore, every 174 hours of unused sick leave adds one full month of creditable service time to your pension multiplier. If you have 1,044 hours of sick leave saved up, that adds a full 6 months of creditable service—boosting your lifetime gross annuity without requiring a single extra day at work.
2. Underestimating the Post-Retirement Health Insurance Shift
While Federal Employees Health Benefits (FEHB) can be carried into retirement provided you meet the 5-year continuous coverage rule, the way premiums are paid changes significantly. As an active employee, your FEHB premiums are paid with pre-tax dollars (premium conversion). In retirement, OPM deducts FEHB premiums using post-tax dollars. This subtle tax shift means health insurance costs consume a slightly larger portion of your net pension income.
3. Misunderstanding the 1.1% Pension Multiplier Bonus
If you retire at age 62 or older with at least 20 years of creditable service, OPM increases your pension multiplier from 1.0% to 1.1%. On a High-3 salary of $120,000 with 22 years of service, that 0.1% increase boosts your gross pension from $26,400 per year up to $29,040 per year—a $2,640 annual boost for life simply by optimizing your retirement date.
Plan Your Federal Retirement with Complete Confidence
Stop relying on fragmented estimates or guessing how much income you will actually have when you leave federal service. By modeling your pension, TSP compound growth, tax withholding, and health benefits in one integrated view, you can retire with complete financial certainty.
The Finance for Feds Retirement Blueprint™ gives you a dynamic, customizable spreadsheet framework designed specifically around official OPM and TSP statutory rules.
👉 Get instant access to the Finance for Feds Retirement Blueprint™ today.
Related Tools
Share This Article
About the Author: Finance for Feds Editorial Team