Traditional vs. Roth TSP: Stop Guessing and Start Optimizing Your Paycheck and Pension
Every pay period, federal employees face one of the most critical financial decisions of their careers: Should you contribute to the Traditional TSP, the Roth TSP, or a combination of both?
It is easy to get bogged down in generic advice. Financial gurus often declare that “Roth is always better because taxes will go up,” while others insist that “Traditional is king because you need the tax deduction today.” The reality is that neither choice is automatically right for every federal employee.
Choosing between Traditional and Roth TSP contributions isn’t just a theoretical debate about tax brackets—it has an immediate effect on your biweekly take-home pay, your current tax bill, and the net spendable wealth you’ll have available in retirement.
Why the Traditional vs. Roth Decision Is Harder for Feds
For private-sector workers, 401(k) decisions are fairly straightforward. But federal employees have a unique financial ecosystem to navigate, including:
-
The FERS Pension Factor: Your taxable FERS pension (and Social Security) creates a guaranteed income floor in retirement. This means you may not drop into as low a tax bracket as you think once you retire.
-
Agency Matching Rules: Regardless of whether you put 100% of your contributions into the Roth TSP, all agency automatic (1%) and matching (up to 4%) contributions go directly into your Traditional TSP account as pre-tax dollars.
-
Paycheck Trade-offs: Because Traditional contributions are pre-tax, every dollar you contribute reduces your current taxable income, leaving more money in your biweekly paycheck today. A Roth contribution comes out after taxes, reducing your take-home pay by a larger amount for the exact same contribution percentage.
If you only focus on the tax savings today, you might leave substantial tax-free wealth on the table for tomorrow. But if you push everything into Roth without looking at your current household budget, you could needlessly strain your biweekly cash flow.
See Today’s Trade-Off—and How the Mix Shapes Tomorrow
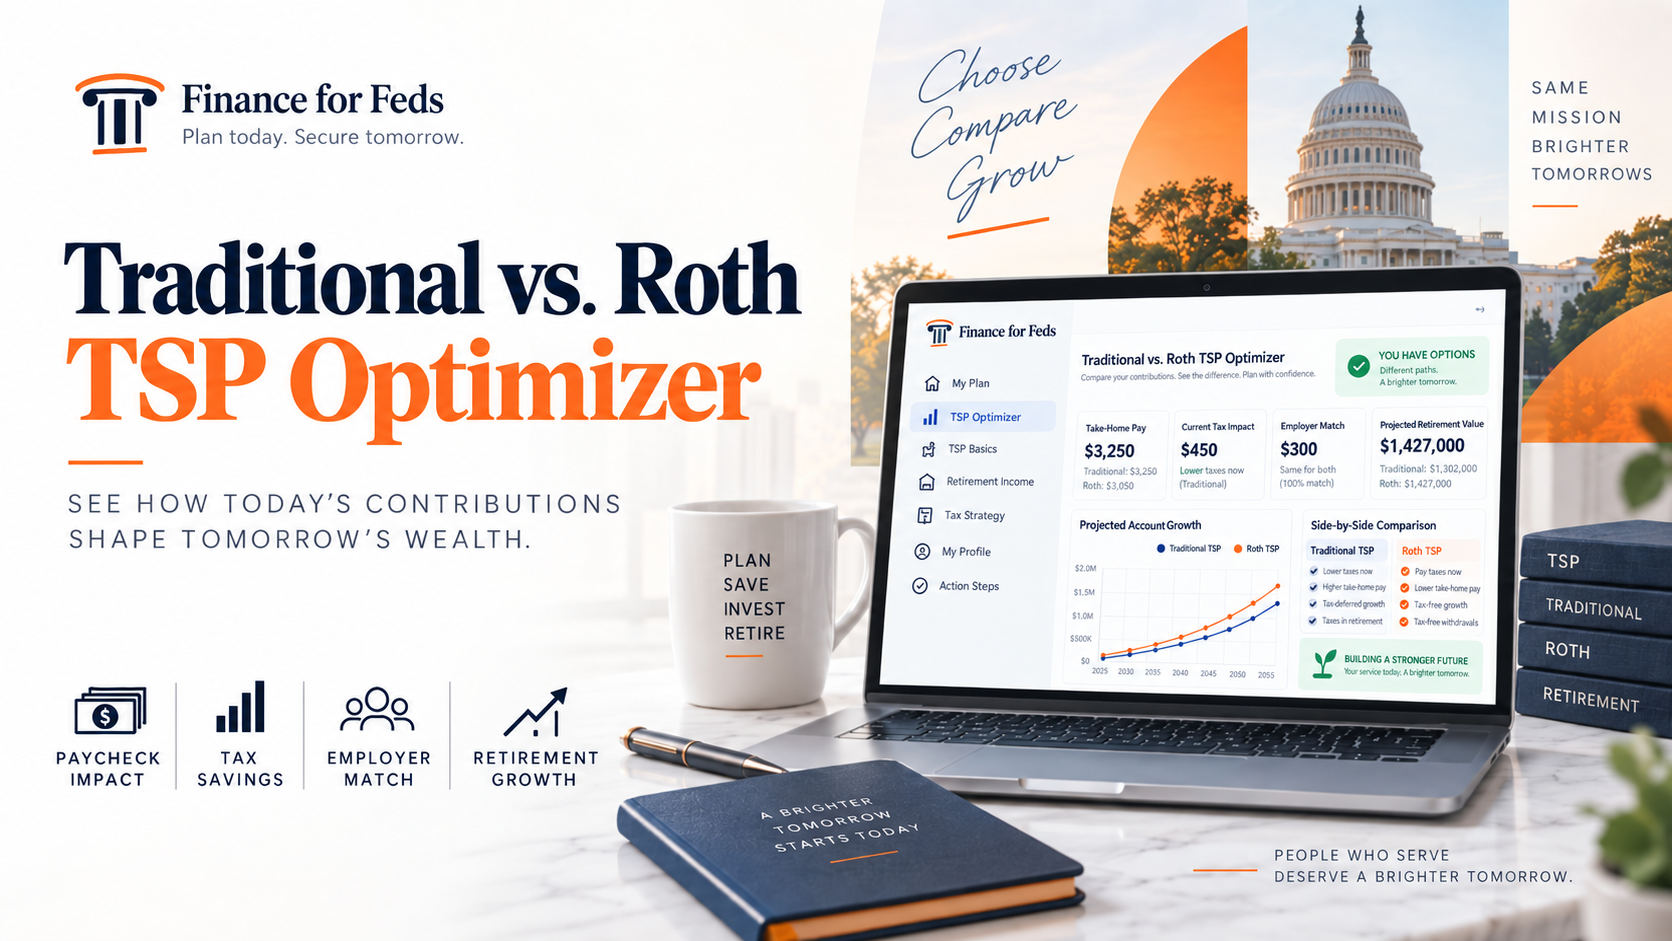
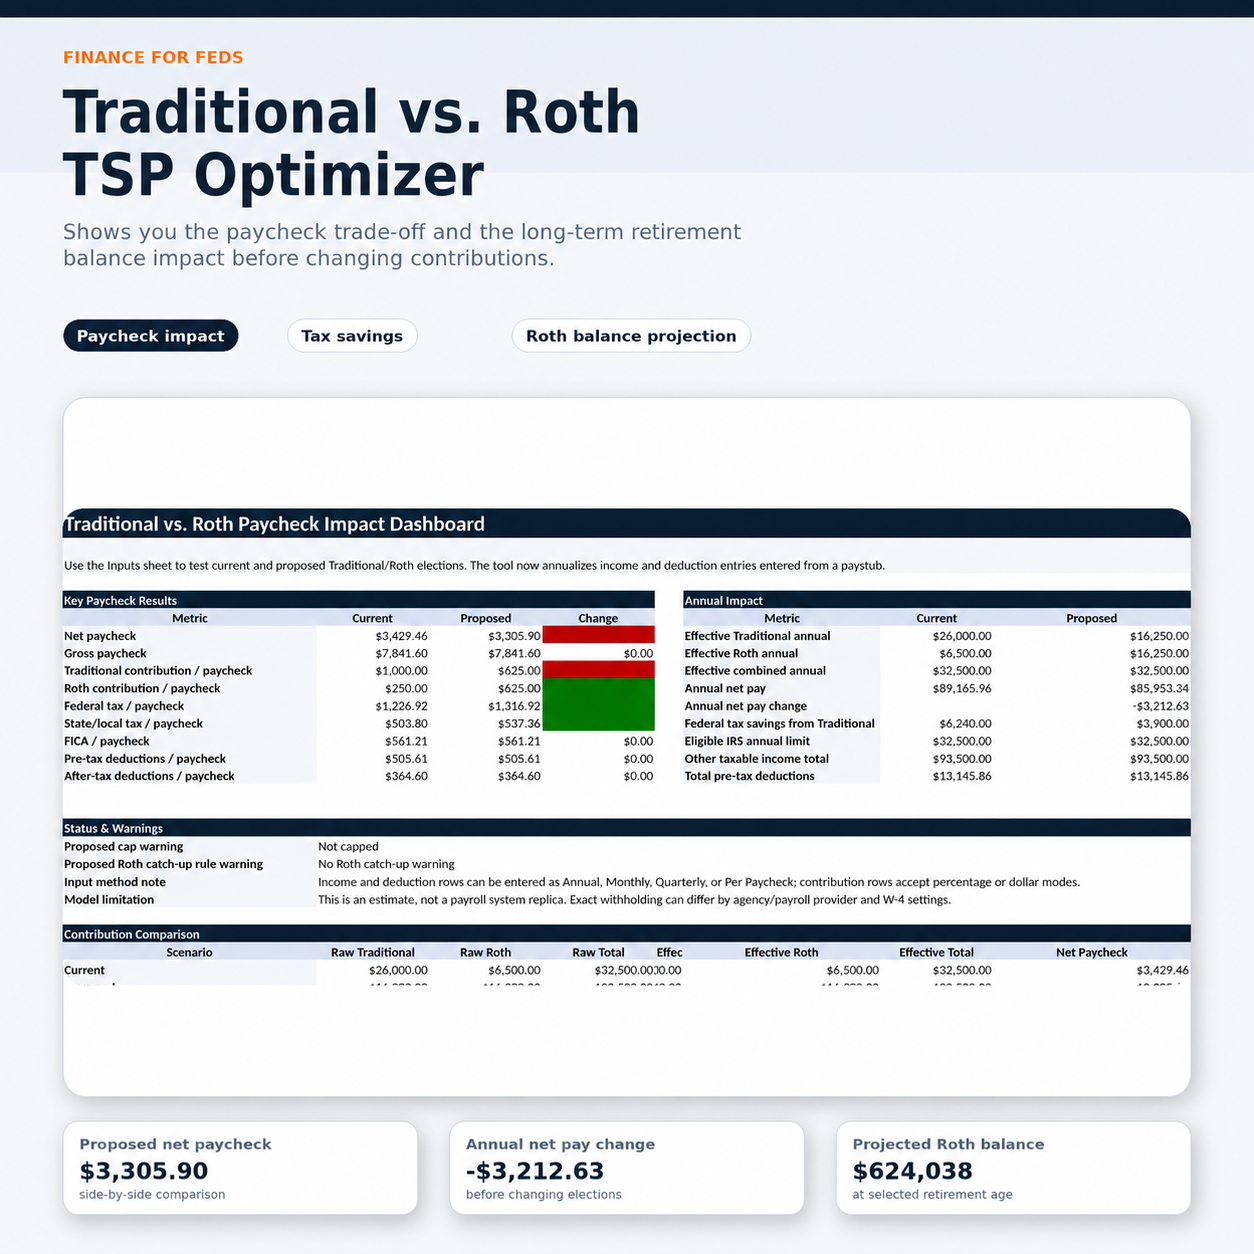
To eliminate the guesswork, we built the Traditional vs. Roth TSP Optimizer.
Instead of relying on rules of thumb, this practical spreadsheet tool analyzes your specific numbers to show you exactly how today’s contribution decisions affect tomorrow’s wealth.
What the Optimizer Analyzes for You:
-
Biweekly Paycheck Impact: See the exact difference in your take-home pay when contributing to Traditional versus Roth at various percentage levels.
-
Current vs. Future Tax Brackets: Compare your current marginal tax rate against your estimated effective tax rate in retirement when combining your TSP, FERS pension, and Social Security.
-
Employer Matching & Growth: Automatically track how your contributions grow alongside agency matching dollars over 10, 20, or 30+ years.
-
Net Spendable Retirement Income: Calculate the bottom-line, after-tax income each strategy generates when it’s time to start taking withdrawals.
Key Questions the Tool Answers in Minutes
-
“How much extra take-home pay do I keep right now if I stick with Traditional contributions?”
-
“If I switch my 5% contribution to Roth, how much will my paycheck actually drop?”
-
“How will having a taxable FERS pension impact the taxes I pay on my TSP withdrawals later?”
-
“What ratio of Traditional vs. Roth gives me the best tax diversification in retirement?”
Stop Guessing. See Your Numbers.
Tax withholding and TSP elections are not isolated decisions. They dictate how much money reaches your bank account every two weeks and shape the financial flexibility you’ll enjoy decades down the road.
Whether you are ten years from retirement or just starting your federal career, seeing your actual numbers side-by-side provides complete clarity.
Get instant access to the Traditional vs. Roth TSP Optimizer and run your numbers today.
Share This Article
About the Author: Finance for Feds Editorial Team