How to Compare FEHB Plans Without Looking Only at the Premium
The Trap of the Single Column
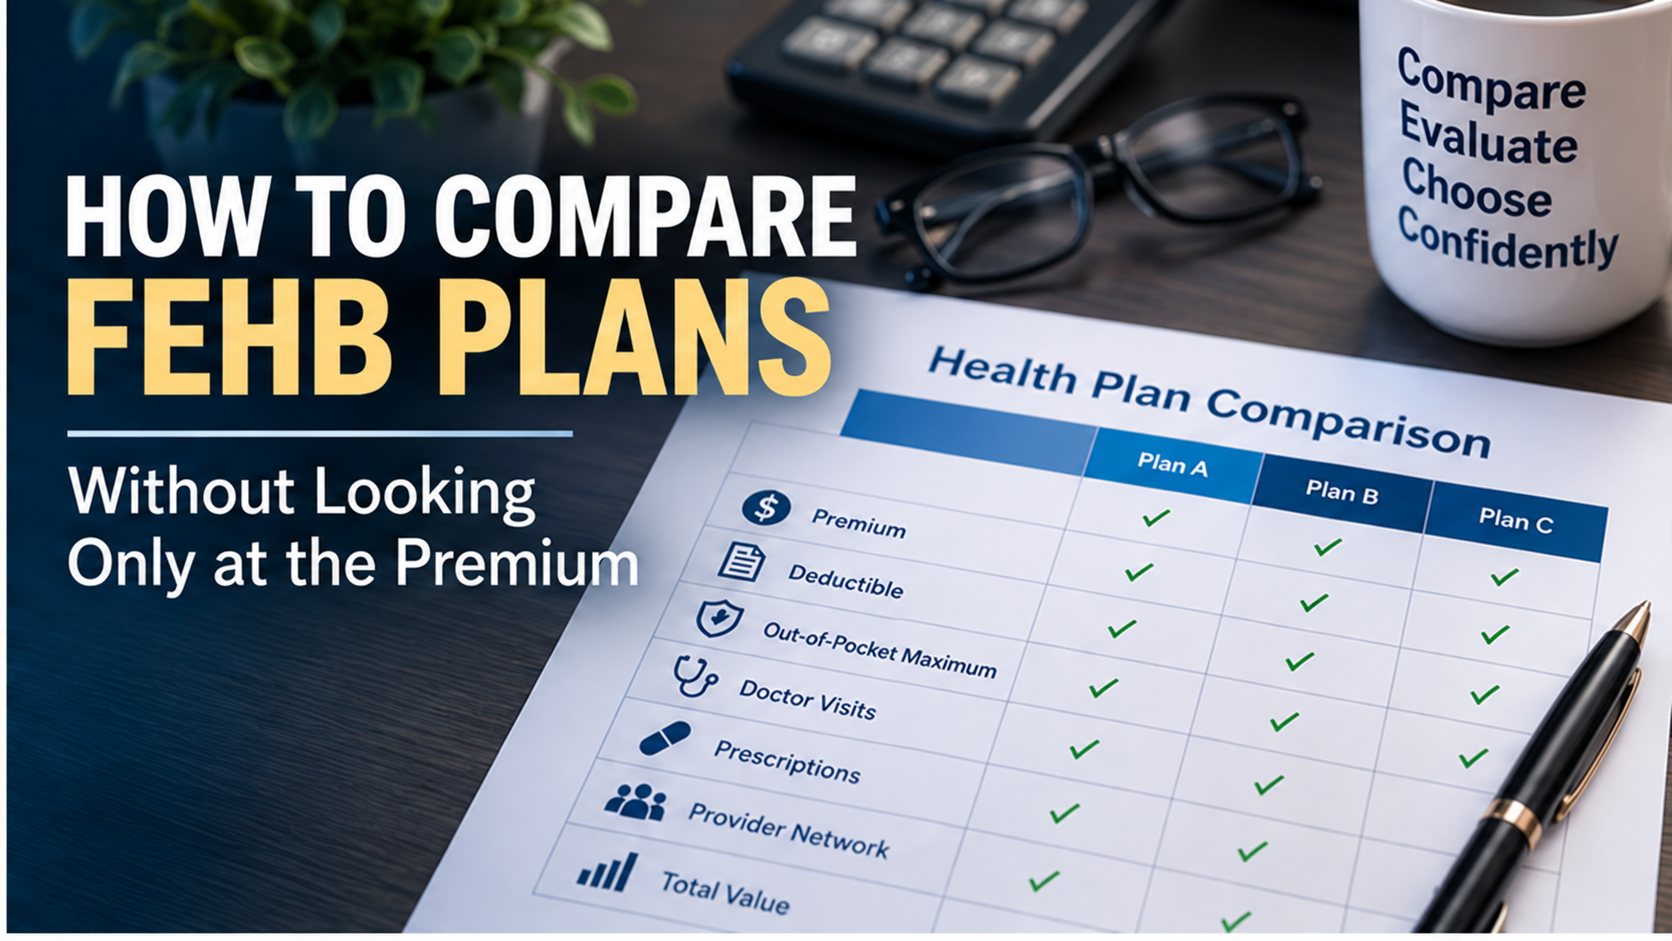
When most federal employees pull up the comparison spreadsheet during Open Season, their eyes lock onto a single, magnetic column: Premium.
It is entirely understandable. Premiums are visible, predictable numbers that quietly vanish from every paycheck. If Plan A costs $120 biweekly and Plan B costs $170, the cheaper plan appears to win by $50 before you even scroll past the first row.
The problem is that health insurance is one of those wonderful products where "cheaper" has a nasty habit of redefining itself the moment you actually need medical care. The goal of Open Season isn't finding the plan with the lowest sticker price; it's finding the one that won't quietly bankrupt you when life happens.
Step One: Do the Annual Math on Premiums
To break out of the biweekly premium trance, convert those numbers into an annual total.
-
Plan A ($120 every two weeks): $120 times 26 = $3,120$ per year
-
Plan B ($170 every two weeks): $170 times 26 = $4,420$ per year
Plan A gives you a clean $1,300 annual advantage right out of the gate. That is a real savings. But the real question is: What are you buying with Plan B's extra $1,300? Are you getting a lower deductible, lower specialist copays, better prescription coverage, or a broader hospital network? If those perks don't matter to your household, stick with Plan A. But if they do, that $1,300 might be the best money you spend all year.
The Deductible and Out-of-Pocket Reality Check
Next, look at the deductible. If Plan A has a $2,000 deductible and Plan B has a $500 deductible, the premium gap starts to shrink. But don't just look at the raw dollar amount—look at what the deductible actually applies to.
Some plans exempt routine office visits or prescriptions from the deductible, handling them with flat copays from day one. High-Deductible Health Plans (HDHPs) usually operate differently, requiring you to clear the full medical and pharmacy deductible before traditional coverage kicks in (aside from preventive care).
To see how the numbers really stack up, test each plan against three different versions of your life:
-
A Healthy Year: Routine physicals, a couple of standard checkups, and basic prescriptions.
-
A Normal Year: A few specialist visits, minor diagnostic testing, and moderate prescription refills.
-
A Bad Year: Surgery, unexpected hospitalization, or an expensive chronic treatment that pushes you right up against the out-of-pocket maximum.
Insurance isn't just about paying for the year you expect; it's about surviving the year you hope never arrives.
Copays vs. Coinsurance: The Coinsurance Gamble
A $35 specialist copay is a beautiful thing. It is clean, predictable, and lets you budget down to the penny. Coinsurance, on the other hand, is a mathematical ambush.
When a plan says you pay 20% coinsurance, your cost depends entirely on what the hospital or doctor decides to bill. Twenty percent of a $200 routine lab draw is $40. Twenty percent of a $10,000 outpatient procedure is $2,000. If your household values predictability, fixed copays are worth a higher premium. If you have the cash reserves to absorb high-variance medical bills in exchange for lower monthly premiums, coinsurance can work in your favor.
Why Your Prescription List Is the Real Plan Decider
If you want to know which health plan will actually cost you the least, open your medicine cabinet before you open the OPM brochure.
Make a literal list of every medication your household takes, then plug them into each plan's prescription pricing tool. If Plan A saves you $1,300 in premiums, but your spouse's specialty medication costs an extra $150 a month under that plan, you've just lost $1,800 at the pharmacy counter. For many families, prescription coverage isn't a footnote—it is the entire comparison. Pay close attention to tier shifts, step-therapy rules, and prior authorization requirements.
Checking Your Network (Because Doctors Move)
A low premium and stellar benefits mean absolutely nothing if your trusted primary care doctor or local hospital system refuses to take the insurance.
Provider contracts expire, medical groups switch networks, and insurance companies re-negotiate behind closed doors. Don't rely on last year's memory. Spend three minutes searching the online provider directory for your doctors, your specialists, and your preferred hospital systems. If you live across state lines or travel frequently, check geographic network coverage too—because an out-of-network emergency room visit is a fantastic way to ruin a Tuesday.
The Government's Backward Pricing Quirks
Federal benefits pricing occasionally defies basic common sense. OPM explicitly warns that in some FEHB plans, the biweekly premium for Self Plus One is actually higher than the rate for Self and Family.
If you cover a spouse or a single child, check both rates. Federal rules explicitly permit employees with one eligible family member to choose Self and Family if it costs less. Never pay an extra penalty just because the enrollment tier with fewer words sounds like it should be cheaper.
Building Your Total-Cost Framework
When the dust settles, stop looking at individual columns and use a simple total-cost formula for your shortlist:
Add up what you expect to spend on care, factor in any plan-funded health savings account pass-throughs, and look at the out-of-pocket maximum for the worst-case ceiling. That gives you a realistic financial picture rather than a guess driven by sticker shock.
The Retirement Perspective
If you are five years or less from retirement, evaluating FEHB changes completely.
Your healthcare needs will likely evolve, Medicare eligibility will loom on the horizon, and your travel habits in retirement might demand nationwide network access. More importantly, your choice today dictates whether you can legally carry that health insurance into retirement. Treat your Open Season choice not just as next year's health plan, but as a foundational pillar of your 30-year retirement strategy.
Related Tools
Share This Article
About the Author: Finance for Feds Editorial Team